


What Are Clean Beauty Shoppers Really Looking For? The Consumer Trends Brands Need to Know
 Ask ten beauty brands what "clean" means and you'll get ten different answers, vegan, cruelty-free, sustainably packaged, dermatologist-tested, sulfate-free, take your pick. But ask the shoppers actually buying these products, and the answer narrows fast: according to PulseAI's Research own consumer research of 1,000 Indian beauty buyers, 45% define clean beauty simply as "organic and natural," and another 35% define it as "free from harmful chemicals." Everything else, the cruelty-free claims, the sustainability messaging, the certifications brands spend heavily to earn, ranks a distant second in the consumer's actual mental model. That gap between what brands emphasize and what shoppers actually mean when they say "clean" is the story this article tells, backed by first-party survey data rather than assumption.
Quick Answer
- Indian clean beauty consumers primarily define "clean" as organic and natural (45%) or free from harmful chemicals (35%), not cruelty-free or sustainable, according to PulseAI's Research 1,000-respondent study.
- Skin sensitivity (81%) and health concerns (68%) drive clean beauty adoption far more than environmental or ethical motivations, which still matter but rank secondary.
- Four consumer personas explain most clean beauty purchase behavior: the Ingredient Investigator, the Eco-Ethical Explorer, the Traditional Revivalist, and the Trend-Led Experimenter.
- Ingredient transparency is nearly universal as a purchase driver, 81% of respondents rate it very or extremely important, yet only 49% are highly familiar with the certifications meant to prove it.
- Ayurvedic ingredients are not a niche preference in India, 93% of respondents use them at least occasionally, and 71% see traditional Indian beauty practices as directly relevant to modern clean beauty.
Introduction
Clean beauty has become one of the most overused and underdefined terms in the beauty industry. Brands slap it on packaging, marketers build entire campaigns around it, and yet the actual consumer definition of what makes a product "clean" rarely gets asked directly, or answered with real data instead of assumption.
This is a different question from how to tell whether a beauty trend is real and worth acting on. That's a validation problem. This article answers a narrower, more immediate question: within the clean beauty category specifically, what are shoppers actually looking for, what do they trust, and what do they avoid. The answers come directly from Smytten PulseAI's own research, "Beauty, But Make It Clean," a 1,000-respondent study into Indian consumers' clean beauty definitions, drivers, and decisions.
By the end of this article, you'll be able to:
- See exactly how Indian consumers define "clean beauty" in their own words, not marketing language
- Understand the four consumer personas driving clean beauty purchase decisions
- Know which ingredients are actively sought, which are avoided, and why transparency matters more than certification familiarity
- Apply real, data-backed positioning strategies instead of generic clean beauty messaging
Why This Topic Matters for Brands
Clean beauty is not a fringe category anymore, it dominates purchase behavior across nearly every core beauty segment. But brands that build strategy on assumptions about what "clean" means routinely misallocate marketing spend on messaging shoppers don't actually prioritize.
- The definition gap is expensive. Brands investing heavily in sustainability or cruelty-free storytelling, while important, are optimizing for a secondary driver. The primary one, ingredient safety and naturalness, gets comparatively less attention in many brand campaigns despite being what most shoppers say clean beauty actually means to them.
- Trust and awareness aren't the same thing. 73% of respondents discover clean beauty products through social media, but only 26% rate social media as highly trustworthy. Dermatologists, at 49% trust, and peer reviews significantly outperform influencer content in actually driving purchase confidence.
- Certification investment may be outpacing consumer understanding. Only 49% of respondents report strong familiarity with certifications like ECOCERT or USDA Organic, even though transparency itself is rated important by 81%. Brands are paying for certifications that a meaningful share of their audience doesn't fully recognize.
- Ayurveda is not a niche play in the Indian market, it's mainstream. 93% of respondents use Ayurvedic ingredients at least occasionally, and younger consumers (18 to 35) are the most engaged with them, not older, more traditional buyers as brands often assume.
Brands that align messaging to what the data actually shows, rather than what "clean beauty" generically implies, capture a meaningfully larger share of purchase intent.
What Are Clean Beauty Consumer Trends?
Clean beauty consumer trends refer to the measurable patterns in how shoppers define, evaluate, and purchase products marketed as clean, natural, or non-toxic, based on their actual stated beliefs, motivations, and behaviors rather than the aspirational language brands use in category marketing.
This distinction matters because "clean beauty" as an industry term and "clean beauty" as a consumer concept frequently diverge. Brand messaging often leads with sustainability, ethics, or certification badges. Consumer research consistently shows the primary driver is closer to home: skin safety, ingredient familiarity, and freedom from specific flagged chemicals.
The Framework: Four Consumer Personas Driving Clean Beauty Decisions
Smytten PulseAI's research identified four distinct personas within the clean beauty audience, each with a different core need and a different strategic lever brands need to pull.
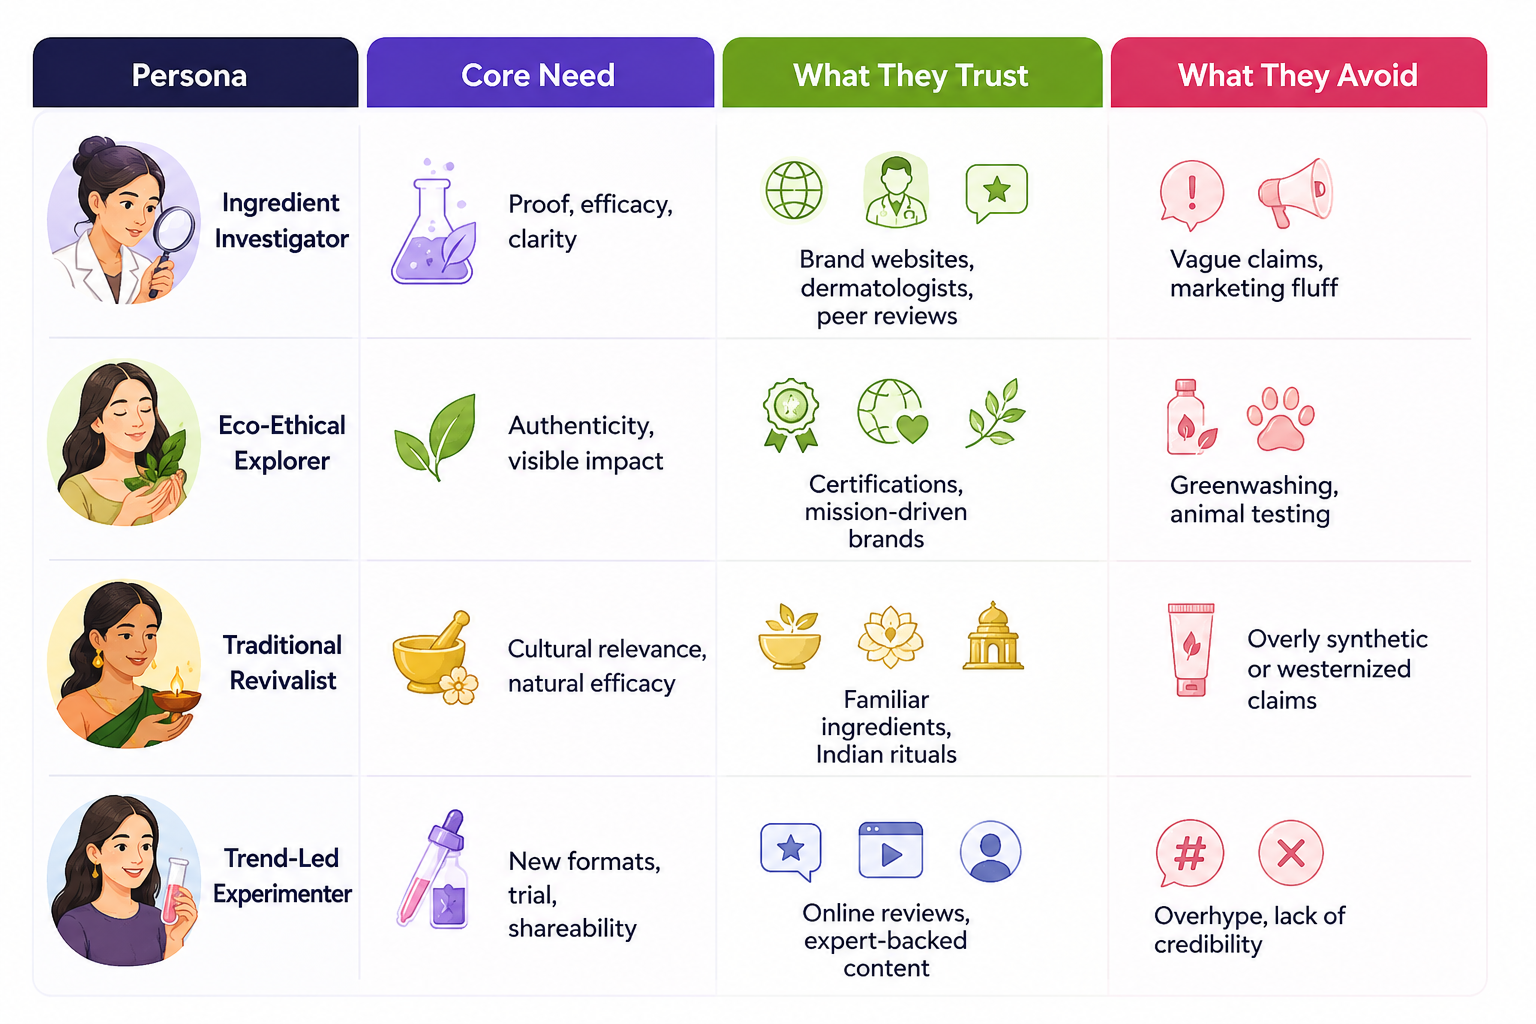
The Ingredient Investigator
Aged 26 to 35, science-first and label-literate. This shopper reads the fine print, seeks clinically-backed ingredients like hyaluronic acid, niacinamide, and peptides, and rates clear ingredient disclosure as extremely important more often than any other segment. They trust brand websites, dermatologists, and peer reviews. They avoid vague claims and marketing fluff. What they're looking for is proof, efficacy, and clarity, not aspirational language.
The Eco-Ethical Explorer
Aged 18 to 30, purpose-led and values-first. Ethics and sustainability drive this shopper's choices, and they favor vegan, cruelty-free, and eco-packaged products even at a price premium. They trust certifications and mission-driven brands, and they actively avoid greenwashing and animal testing. Authenticity and visible impact matter more to this persona than to any other segment.
The Traditional Revivalist
Aged 25 to 40, heritage-aligned and nature-rooted. This persona embraces Ayurvedic and traditional Indian ingredients like turmeric, neem, and sandalwood, viewing clean beauty as a modern return to ancient wisdom rather than a Western import. They trust familiar ingredients and Indian rituals, and they avoid overly synthetic or westernized claims. Cultural relevance and natural efficacy are what they're actually shopping for.
The Trend-Led Experimenter
Aged 18 to 25, curious and digital-first. Highly engaged on social platforms, this segment is driven by novelty, aesthetics, and peer buzz. Discovery is often influencer-led, but purchase is ultimately guided by reviews and real experience, not the influencer content that drove initial awareness. They trust online reviews and expert-backed content over overhype, and they're looking for new formats, trial options, and shareable, Instagrammable products.
Comparison: What Each Persona Actually Wants From a Brand
Real-World Findings From the Data
What "Clean" Actually Means to Shoppers
When asked to define clean beauty directly, 45% of respondents chose "organic and natural" and 35% chose "free from harmful chemicals." Cruelty-free came in at just 14%, and sustainably produced at only 6%. The strategic implication is direct: the clean beauty narrative in India remains strongly ingredient-focused, and ethical production or sustainability messaging, while valuable, is not yet what most consumers mean when they say a product is "clean."
The Ingredients Shoppers Actively Seek, and Actively Avoid
Hyaluronic acid (70%) and aloe vera (69%) top the list of actively sought ingredients, closely followed by niacinamide (68%) and turmeric (66%), with neem and sandalwood also seeing high traction. On the avoidance side, parabens (76%), sulfates (72%), and artificial colors (66%) lead the list, with synthetic fragrances, silicones, and phthalates also ranking high. This is a hybrid palette, shoppers want both clinically proven actives and familiar traditional botanicals, not one or the other.
The Transparency and Certification Gap
81% of respondents rate ingredient transparency as very or extremely important, with only 1% saying it doesn't matter. Yet only 49% report being very or extremely familiar with the certifications, like ECOCERT or USDA Organic, that are meant to signal that transparency. Nearly a third of respondents fall into low-to-moderate certification familiarity. This is a real strategic opening: brands that invest in explaining what a certification actually means, not just displaying the logo, address a gap most competitors are leaving unaddressed.
Ayurveda Is a Mainstream Preference, Not a Niche One
93% of respondents integrate Ayurvedic ingredients into their routines at least occasionally, and 58% do so often or very often. Even more notably, this engagement skews toward younger consumers (18 to 35) rediscovering indigenous ingredients, not older, more traditional buyers as brand strategy often assumes. 71% of all respondents agree or strongly agree that traditional Indian beauty practices are relevant to modern clean beauty, with only 4% disagreeing.
PulseAI Research Insight
Our own research into the Indian clean beauty consumer surfaced a pattern brands consistently underestimate: the gap between what gets marketed and what actually drives trust.
A few findings worth building strategy around directly:
- Skin sensitivity, not sustainability, is the leading motivator. 81% of respondents cite skin sensitivity as a driver of clean beauty adoption, and 68% cite health concerns. Environmental consciousness (55%) and ethical considerations (53%) matter, but they're reinforcing factors, not the primary reason most shoppers reach for a clean beauty product in the first place.
- Discovery and trust run through different channels entirely. Social media drives 73% of product discovery, but only 26% consider it highly trustworthy. Dermatologists, at 49% trust, meaningfully outperform every other information source, including friends and family, brand websites, and influencer content. Brands over-indexing on influencer partnerships without a credible expert-backed layer are optimizing for reach, not conversion.
- Skincare and haircare are the entry points, not the whole opportunity. 94% of respondents purchase clean skincare and 73% purchase clean haircare, while fragrance (47%) and makeup (57%) trail meaningfully. This is genuine white space for brands willing to bring ingredient-led storytelling and clean reformulation into more sensory-driven, currently underserved categories.
- Hybrid formulation is where the real growth is. The strongest performing ingredient positioning doesn't pick a side between Ayurvedic tradition and clinical science, it combines both. Respondents actively seek hyaluronic acid and turmeric in the same routine, and brands that reflect that hybrid mindset in formulation and messaging consistently outperform those leaning exclusively natural or exclusively clinical.
This connects directly to the natural vs synthetic ingredient debate covered elsewhere in this research library. This data confirms it empirically: Indian consumers aren't choosing between natural and synthetic, they're actively seeking both in a single hybridized definition of what clean beauty means to them.
How Brands Can Use This in Practice
A simple checklist based directly on the research findings:
- [ ] Lead with ingredient safety language, not sustainability language, as the primary message. "Free from harmful chemicals" resonates with more consumers than cruelty-free or sustainability claims alone; use the latter as supporting, not lead, messaging.
- [ ] Formulate and market hybrid actives. Pair clinically-backed ingredients like niacinamide or hyaluronic acid with familiar botanicals like turmeric or neem, this dual positioning consistently outperforms either approach alone.
- [ ] Invest in certification education, not just certification badges. With only 49% highly familiar with what certifications actually mean, a brand that explains its ECOCERT or organic labeling in plain language builds more trust than one that simply displays the logo.
- [ ] Balance influencer reach with dermatologist-backed credibility. Use social platforms for discovery, but layer in expert endorsement and visible clinical backing to convert that awareness into actual purchase trust.
- [ ] Don't treat Ayurveda as a heritage-only play. Younger consumers are the most engaged with Ayurvedic ingredients; modernized formats, not purely traditional packaging, are what capture that demand.
- [ ] Look beyond skincare for category expansion. Fragrance and makeup remain underdeveloped in the clean beauty conversation relative to skincare and haircare, representing real category white space for ingredient-led brands.
Related Concepts Marketers Should Know
- Natural vs Synthetic Beauty Ingredients: the broader consumer psychology behind why shoppers trust certain ingredient categories over others, directly reflected in this data.
- Trend Validation: the process of confirming whether a beauty trend observed in the market is commercially meaningful before investing against it.
- Clean Beauty vs Green Beauty: clean beauty typically emphasizes ingredient safety and health, while green beauty leans more heavily on environmental sustainability, two overlapping but distinct positioning strategies this data helps separate.
- Ingredient Literacy: the degree to which consumers understand and evaluate specific ingredients rather than relying on broad category labels like "natural" or "clean," a key driver behind the Ingredient Investigator persona.
- Certification Fatigue: the growing gap between the number of certifications brands display and consumers' actual familiarity with what those certifications mean, a real risk highlighted directly in this research.
- Beauty Brand Positioning: how these product-level preferences roll up into a broader brand perception strategy, covering premium vs affordable, clinical vs natural, and other core positioning tensions.
FAQs
1.What do Indian consumers actually mean when they say "clean beauty"?
Based on direct survey data, most define it as organic and natural (45%) or free from harmful chemicals (35%). Cruelty-free and sustainability definitions exist but are secondary, chosen by only 14% and 6% of respondents respectively.
2.Do clean beauty consumers prefer natural ingredients over clinically-backed ones?
Not exclusively. Research shows strong demand for both, hyaluronic acid and niacinamide rank alongside turmeric and neem among the most actively sought ingredients, indicating a hybrid preference rather than a binary choice.
3.Is sustainability important to clean beauty shoppers?
Yes, but it's a secondary driver. Environmental consciousness (55%) and ethical considerations (53%) matter to over half of respondents, but skin sensitivity (81%) and health concerns (68%) are consistently the primary motivators behind clean beauty adoption.
4.How important is ingredient transparency to purchase decisions?
Extremely important. 81% of respondents rate it as very or extremely important, with only 1% saying it doesn't matter, making it one of the most consistent purchase drivers in the research.
5.Do younger or older consumers engage more with Ayurvedic beauty ingredients?
Younger consumers, specifically the 18 to 35 age range, show the highest engagement with Ayurvedic ingredients and routines, challenging the assumption that traditional ingredients appeal mainly to older buyers.
6.Which clean beauty categories have the most room for brand growth?
Fragrance (47%) and makeup (57%) show meaningfully lower clean beauty engagement than skincare (94%) and haircare (73%), representing clear white space for brands willing to bring ingredient-led, clean-labeled innovation into more sensory-driven categories.
Read Similar Blogs
Read Similar Blogs
10 Market Research Techniques That Actually Deliver InsightsThe 4 Types of Consumer Behaviour Every Marketer Must KnowApplication of Consumer Behaviour: How Brands Turn Insights Into GrowthConsumer Research Process: A Step-by-Step Workflow for Better InsightsFactors Influencing Consumer Behaviour and the One Your Research Is Almost...How to Create a Survey Questionnaire That Delivers Reliable ResultsDifference Between Research Method and Research Methodology: Clearing Up the...Where Market Research Is Headed: Trends Brands Can’t IgnoreQualitative Research Questions: How to Ask Better Questions for Deeper Consumer...Qualitative Consumer Research: Why Customers Behave This WayConsumer Research Methodology: A Step-by-Step GuideConfusing Survey Questions: 25 Examples and How to Fix ThemWhy Customers Buy: Consumer Behaviour Insights for BrandsQualitative Research Techniques: How to Extract Better Consumer InsightsObjectives of Marketing Research: The Real DistinctionQuantitative vs Qualitative Consumer Research: Which One?Consumer Insights Platform: What It Is and How to Choose OneStructured vs Unstructured Questionnaire: Which to UseHow to Build a High-Performing Marketing Research Team That Drives Business... Consumer Insights Research: Methods, Frameworks, and Best Practices
10 Market Research Techniques That Actually Deliver InsightsThe 4 Types of Consumer Behaviour Every Marketer Must KnowApplication of Consumer Behaviour: How Brands Turn Insights Into GrowthConsumer Research Process: A Step-by-Step Workflow for Better InsightsFactors Influencing Consumer Behaviour and the One Your Research Is...How to Create a Survey Questionnaire That Delivers Reliable ResultsDifference Between Research Method and Research Methodology: Clearing Up...Where Market Research Is Headed: Trends Brands Can’t IgnoreQualitative Research Questions: How to Ask Better Questions for Deeper...Qualitative Consumer Research: Why Customers Behave This WayConsumer Research Methodology: A Step-by-Step GuideConfusing Survey Questions: 25 Examples and How to Fix ThemWhy Customers Buy: Consumer Behaviour Insights for BrandsQualitative Research Techniques: How to Extract Better Consumer InsightsObjectives of Marketing Research: The Real DistinctionQuantitative vs Qualitative Consumer Research: Which One?Consumer Insights Platform: What It Is and How to Choose OneStructured vs Unstructured Questionnaire: Which to UseHow to Build a High-Performing Marketing Research Team That Drives... Consumer Insights Research: Methods, Frameworks, and Best Practices